
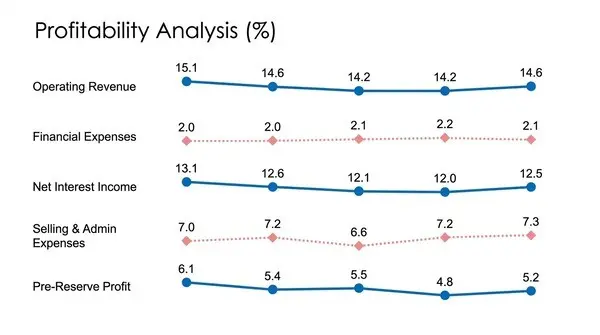
Samsung Card failed to defend its profitability in the first quarter of this year despite an increase in card usage volume. While the company's top line expanded, the pace of cost growth outstripped it.
According to Samsung Card on the 29th, net profit for Q1 came to $105.97 million (₩156.3 billion), down 15.3% from the same period a year earlier. Operating profit was $142.37 million (₩210 billion), a decline of 14.2%. Revenue totaled $871.73 million (₩1.2858 trillion), up 20.4%.
In terms of transaction volume, growth was pronounced. Total transaction volume for Q1 was $32.09 billion (₩47.3345 trillion), up 9.3% year on year. Card business transaction volume rose 9.4% to $31.96 billion (₩47.1438 trillion). Credit sales accounted for $28.79 billion (₩42.4597 trillion) and the financial segment for $3.18 billion (₩4.6841 trillion). Installment and lease business transaction volume was $129.29 million (₩190.7 billion), down 13.9%.
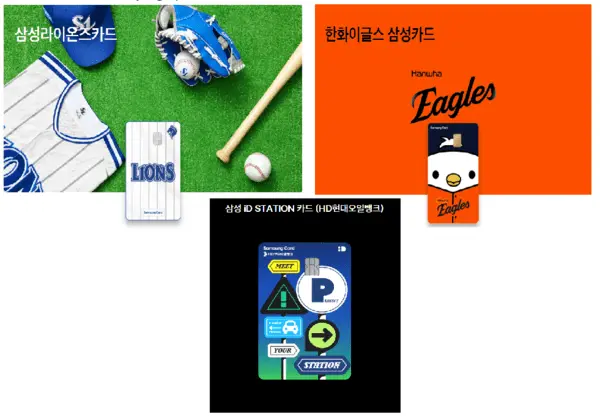
The expansion in transaction volume was driven by partnership strategies. Since the inauguration of President and CEO Kim I-tae, Samsung Card has moved quickly to expand its PLCC (private label credit card) lineup. Early this year, it launched five co-branded cards with Woori Bank, followed by the release of Hanwha Eagles and Nexen Tire cards. It is also preparing to launch PLCCs with Marriott International and Musinsa.
The compression of profitability was attributable to the expansion of costs. Operating expenses for Q1 totaled $606.10 million (₩894 billion), up 37.9% year on year, a pace nearly twice the revenue growth rate of 20.4%. Financial costs, credit loss provisions, and selling and general administrative expenses all rose. SG&A also exceeded market expectations, coming in at $362.78 million (₩535.1 billion), with the bulk attributable to personnel costs.
Asset quality remained at a sound level. The delinquency rate for accounts more than one month overdue was 0.92%, down slightly from the end of last year (0.94%). The quarterly credit loss rate was 2.43%, edging down from the prior quarter. Indicators improved as assets grew with a focus on credit sales, which carry sound asset quality metrics.
A Samsung Card official said the company expects market volatility in the funding market and other risk factors to persist beyond Q2, and that it intends to focus on proactively addressing risk factors and strengthening core business competitiveness.
(Reference: USD equivalent, KRW/USD ≈ ₩1,475. Applied as ₩1,475 = $1.00 for convenience.)


댓글 (0)
댓글을 작성하려면 로그인이 필요합니다.
로그인하기